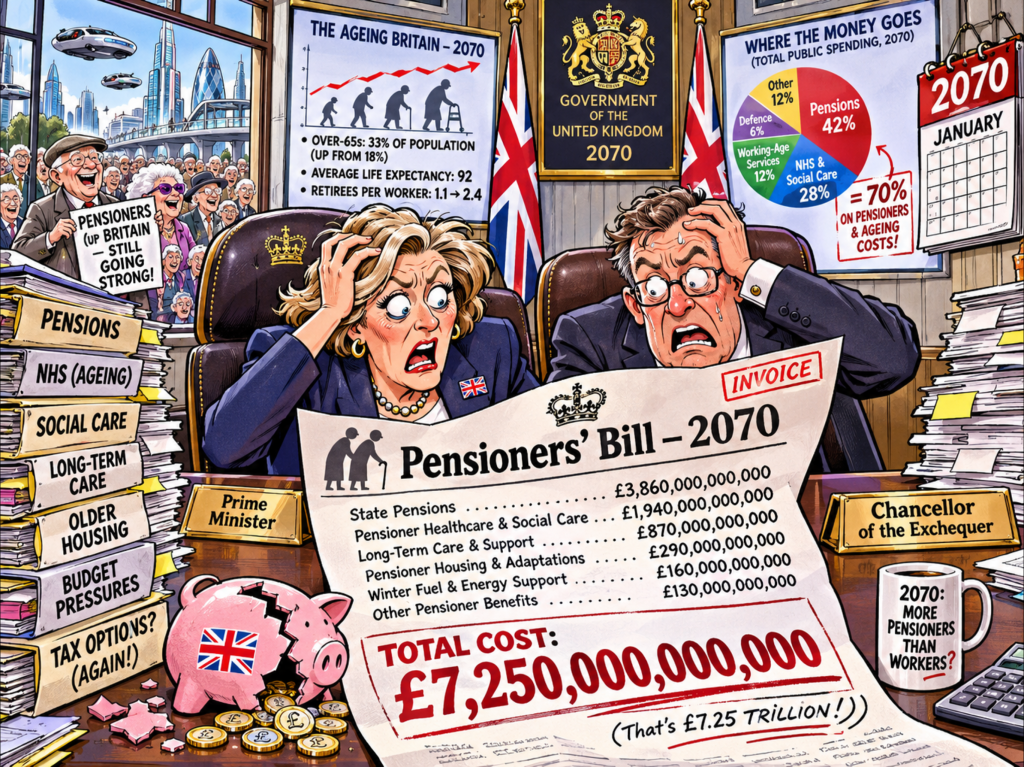
Britain has apparently discovered the secret to keeping its ageing population financially afloat: recruit more workers from overseas, collect their taxes, fill the gaps in the NHS and social care, and declare the problem solved.
Brilliant! Another triumph of Westminster economics. 👏
Just one tiny detail seems to have escaped the political masterminds.
Those workers will eventually get old too!
Yes, astonishingly, people recruited at 25 don’t remain 25 forever. They eventually reach retirement age, develop healthcare needs and may require support from the very public services their taxes once helped finance.
And when that happens, who’s paying the bill?
Welcome to Britain’s Pension Time Bomb, where the solution to today’s ageing population might just be creating another generation of pensioners tomorrow. 💷💥
🏛️ Westminster’s Magic Money Trick: Today’s Taxpayer, Tomorrow’s Treasury Headache!
Let’s give credit where it’s due.
Overseas workers have made enormous contributions to Britain’s NHS and social care system. They staff hospitals, care homes and essential services, pay taxes and National Insurance, and help keep the country functioning.
Without them, parts of the system would face even greater difficulties.
But here’s where the economic fairy tale starts developing a rather expensive plot twist.
Many healthcare assistants and social care workers are relatively low-paid. Building a substantial private pension on modest earnings, particularly while meeting Britain’s soaring housing and living costs, is hardly straightforward.
And while someone who has spent fewer qualifying years in Britain may receive a smaller State Pension, that doesn’t necessarily mean they’ll cost the taxpayer less overall.
Why?
Because a smaller pension doesn’t automatically mean smaller living expenses.
Rent still needs paying. Heating still costs money. Healthcare doesn’t become free to provide simply because someone’s retirement income is limited.
Depending on their eligibility and circumstances, pensioners with insufficient retirement income may qualify for means-tested assistance, housing support or publicly funded care.
So the Treasury might save money on someone’s State Pension only to face additional expenditure elsewhere.
It’s rather like celebrating because you’ve saved £20 on your electricity bill while ignoring the £2,000 repair bill arriving through the letterbox. 📬💸
⏳ Thirty Years of Contributions — Then the Retirement Reality!
According to the Migration Observatory’s June 2026 analysis, health and care workers are estimated to make positive net fiscal contributions during their first 30 years in Britain, before becoming a net fiscal cost as the cohort ages.
Now, this doesn’t mean overseas workers are automatically a lifetime financial burden.
Some arrive young and contribute for decades. Some earn substantial salaries and pay significant amounts in tax. Others return to their countries of origin before retirement.
The financial outcome depends on earnings, age, family circumstances, employment history, length of residence and eventual retirement arrangements.
But the underlying issue deserves serious scrutiny.
If Britain’s answer to an ageing population is continuously increasing the number of working-age taxpayers, what happens when those taxpayers join the ageing population themselves?
Do we recruit another generation to support them?
And another generation after that?
At what point does the whole arrangement begin to resemble a demographic game of musical chairs, except the chairs are NHS beds and the music is the Treasury screaming? 🎶🏥
📉 The OBR’s Warning: The Future Is Getting Older, and the Bill Is Getting Bigger!
The Office for Budget Responsibility’s July 2026 report projects increasing pressure on Britain’s public finances over the coming 50 years.
An ageing population, rising healthcare expenditure and growing State Pension costs are all expected to place substantial demands on government spending.
In other words, the financial challenges aren’t some distant fantasy dreamed up by pessimists.
They’re already part of the country’s long-term fiscal outlook.
Yet Westminster continues behaving as though the next election is the outer limit of human civilisation.
Politicians love announcing how many new workers have been recruited.
They love announcing additional funding.
They absolutely adore standing in front of hospitals wearing hard hats and looking thoughtfully at equipment they couldn’t identify if their careers depended on it. 🏥📸
But ask what Britain’s pension, housing, healthcare and social care commitments might cost in 2050, 2060 or 2070, and suddenly the enthusiasm for detailed answers becomes considerably less impressive.
Because recruiting workers today is not the same thing as securing the nation’s finances tomorrow.
And population growth without sufficient productivity growth, infrastructure investment and sustainable retirement provision risks creating additional financial pressures rather than eliminating existing ones.
💷 The Great Pension Illusion: Keep Adding Taxpayers and Hope Nobody Retires!
There is nothing inherently wrong with immigration contributing to economic growth.
Indeed, workers who arrive young, earn good salaries and contribute over many decades can deliver substantial benefits to the public finances.
But immigration is not a magic wand that makes demographic ageing disappear.
A sustainable system needs more than an expanding workforce.
It needs stronger productivity, better wages, affordable housing, effective pension saving and public services capable of meeting future demand.
Otherwise, we’re simply moving financial obligations further down the road.
And Britain has already become remarkably skilled at kicking expensive problems into the future.
National debt? Tomorrow’s problem.
Social care reform? Tomorrow’s problem.
Pension sustainability? Tomorrow’s problem.
Apparently, Britain’s entire long-term economic strategy can be summarised in three words:
“Someone else’s problem!” 🙄
Unfortunately, that someone else may be our children and grandchildren.
🚨 Dear Treasury: Where’s the Full Lifetime Bill?
Here’s the question government should be answering.
If Britain increasingly relies on overseas recruitment to sustain public services and tax revenues today, has the Treasury calculated the full lifetime financial impact of that policy?
Not simply how much tax workers contribute during their first five or ten years.
Not just how many vacancies they fill.
And certainly not another carefully polished political announcement celebrating recruitment figures.
We need transparent projections of both lifetime contributions and lifetime costs.
What will pension entitlements cost?
What additional means-tested assistance might be required?
What are the projected NHS and social care costs as different groups age?
What happens to housing demand and public service expenditure?
How do the calculations change when workers have different salaries, arrival ages, family circumstances and lengths of residence?
And critically, what does the overall financial picture look like in 2050, 2060 and 2070?
These are not unreasonable questions.
They are precisely the questions any government claiming to manage the nation’s finances responsibly should be prepared to answer.
This isn’t about blaming migrant workers for growing old. British-born workers retire and require public services too.
It’s about challenging politicians who promote short-term economic benefits without always explaining the long-term obligations.
Because whether someone was born in Birmingham, Bradford, Mumbai or Manila, the laws of ageing remain remarkably consistent.
Everybody gets older. And somebody has to fund the system.


Leave a Reply